United Kingdom

UK Social Housing: Government-Funded Rent

Fully renovated, freehold homes in the North East of England — pre-leased to housing associations, with rent funded by government-backed arrangements for up to 25 years and zero landlord burden.

£127,500
Entry, from — fully renovated freehold
10–12%
Net, government-funded
Day 91
Income contracted from
25yr
Lease, up to — CPI-linked reviews, capped
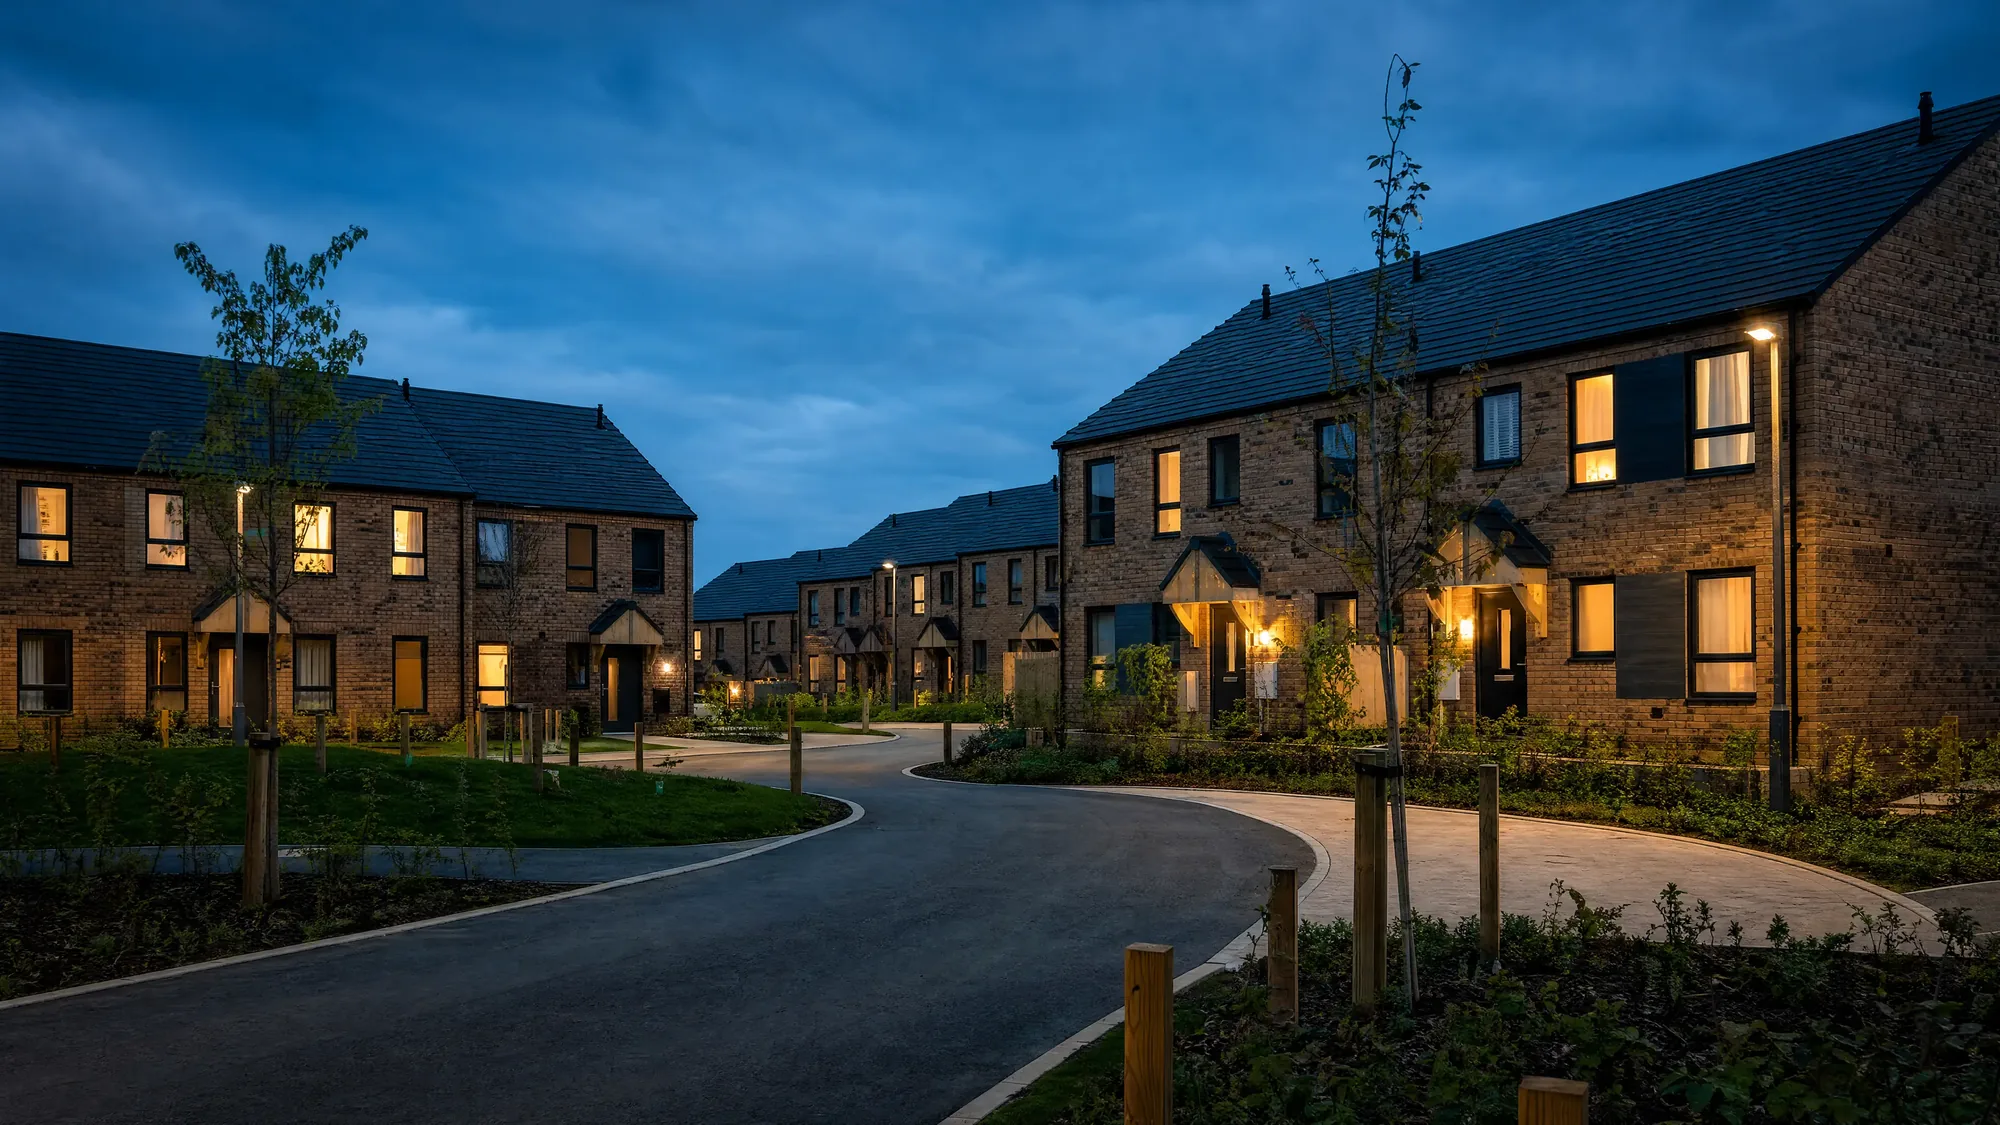
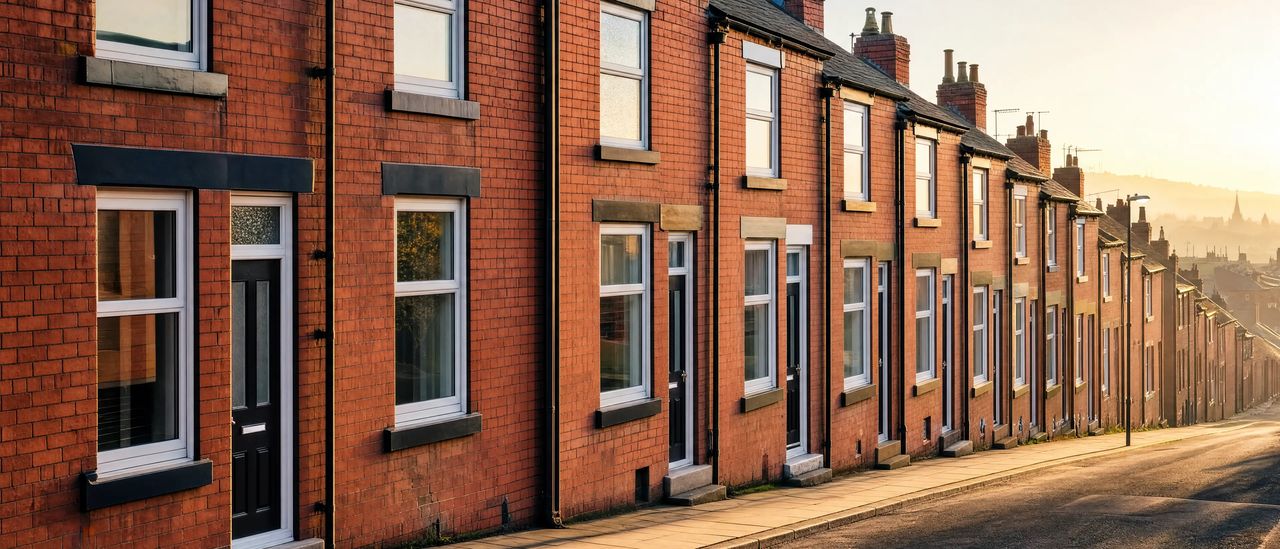
A renovated row of terraced houses in the North East of England in morning light
Fully renovated, freehold, lease in place — the stock as it is delivered.
Why social housing

Why Invest in UK Social Housing?

The UK’s social housing shortage has created one of the most stable, government-supported property income models in Europe — and your tenant is an institution, not an individual.

Backed by national demand

A 4.3 million-home shortage, growing by at least 90,000 a year. Local authorities spend over £1.5B annually housing vulnerable people — demand is structural, not cyclical.

Government-funded income

Rent arrives from a housing association under a legally binding lease — fixed net yield, contracted from Day 91.

Zero management costs

The association handles maintenance, repairs and tenant turnover. No letting agents, no voids to cover, no calls at midnight.

Freehold, hands-off ownership

Fully renovated freehold units under long-term lease agreements — the landlord burdens are removed by design, not by promise.

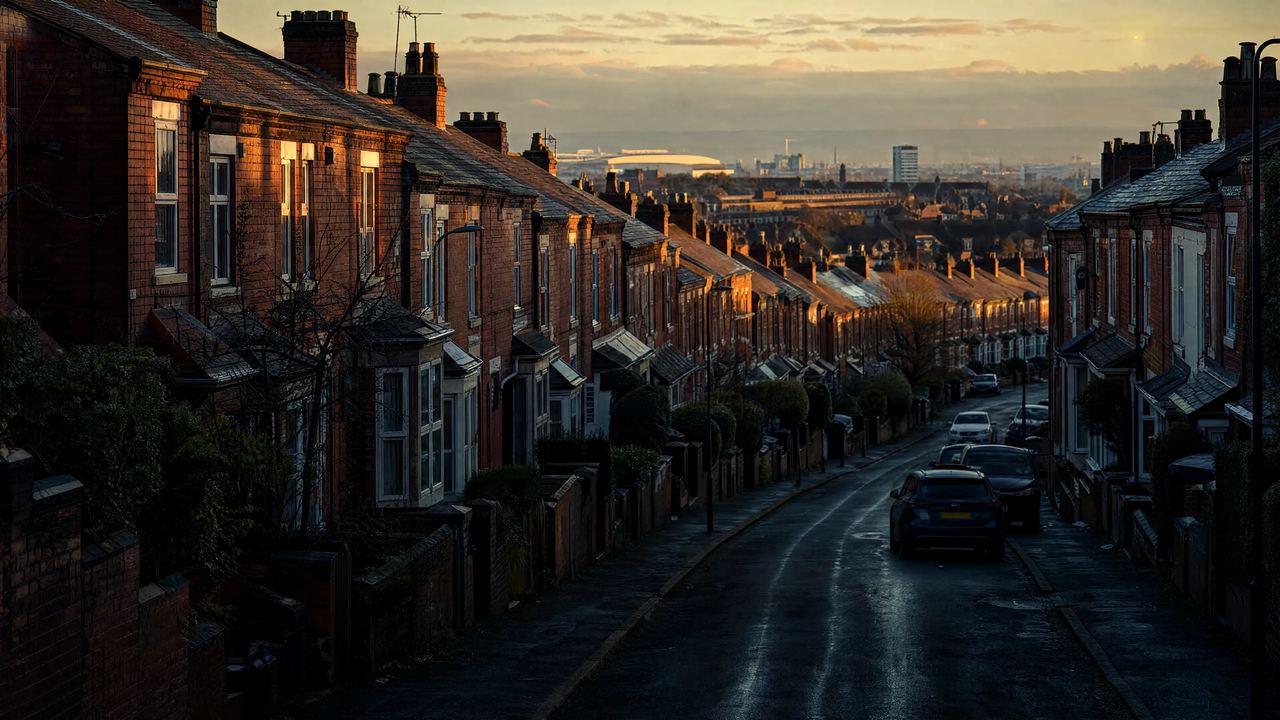
Red-brick terraced housing in northern England at dusk
The North East

Where Our UK Homes Sit

The North East offers entry prices far below London or Manchester, structural housing demand, and ongoing public investment in transport, schools and housing renewal.

Sunderland

Regeneration-led coastal city; among the UK’s most affordable entry points with sustained association demand.

Hartlepool

Marina-side renewal and public housing investment keep long-term association tenancy deep and stable.

Middlesbrough

Transport and education investment underpins rental demand across the town’s refurbished terraced stock.

The model

Four Steps, Nothing to Operate

01
Buy freehold
Fully renovated, tenant-ready unit
02
Lease in place
Pre-leased to a housing association
03
Income from Day 91
Government-funded rent, contracted
04
Hold, hands-off
Lease runs up to 25 years

All units are held as freehold and delivered fully renovated, with the association lease in place at completion.

Case study

One House, From Deposit to Day 91

A single £127,500 terrace in Sunderland, followed through the programme’s own structure — reserve, exchange, complete, first payment. Every figure below is the brochure’s arithmetic, nothing modelled on top.

Reserved — £5,000

01

A fully renovated two-bed terrace is reserved for £5,000, deducted from the £127,500 price. Independent solicitors run the purchase remotely; nothing else is due yet.

Exchanged — 50% on contract

02

Contracts exchange on £63,750. One-time costs fall at purchase: legal ~£1,550 and stamp duty at 3–5% (£3,825–£6,375). The structure is cash-only, by design.

Completed — inside 90 days

03

The balance of £58,750 lands on delivery, the £5,000 reserve already deducted. Freehold registers in the owner’s name with the association lease in place. Total capital in: £132,875–£135,425.

Earning — from Day 91

04

The first contracted payment arrives on Day 91, regardless of placement status. From then: £12,750–£15,300 net a year (£1,062–£1,275 a month), with management, maintenance and repairs all carried by the provider and CPI-linked uplifts capped.
91days
From completed purchase to first contracted rent — the income clock starts with ownership, not tenant placement.
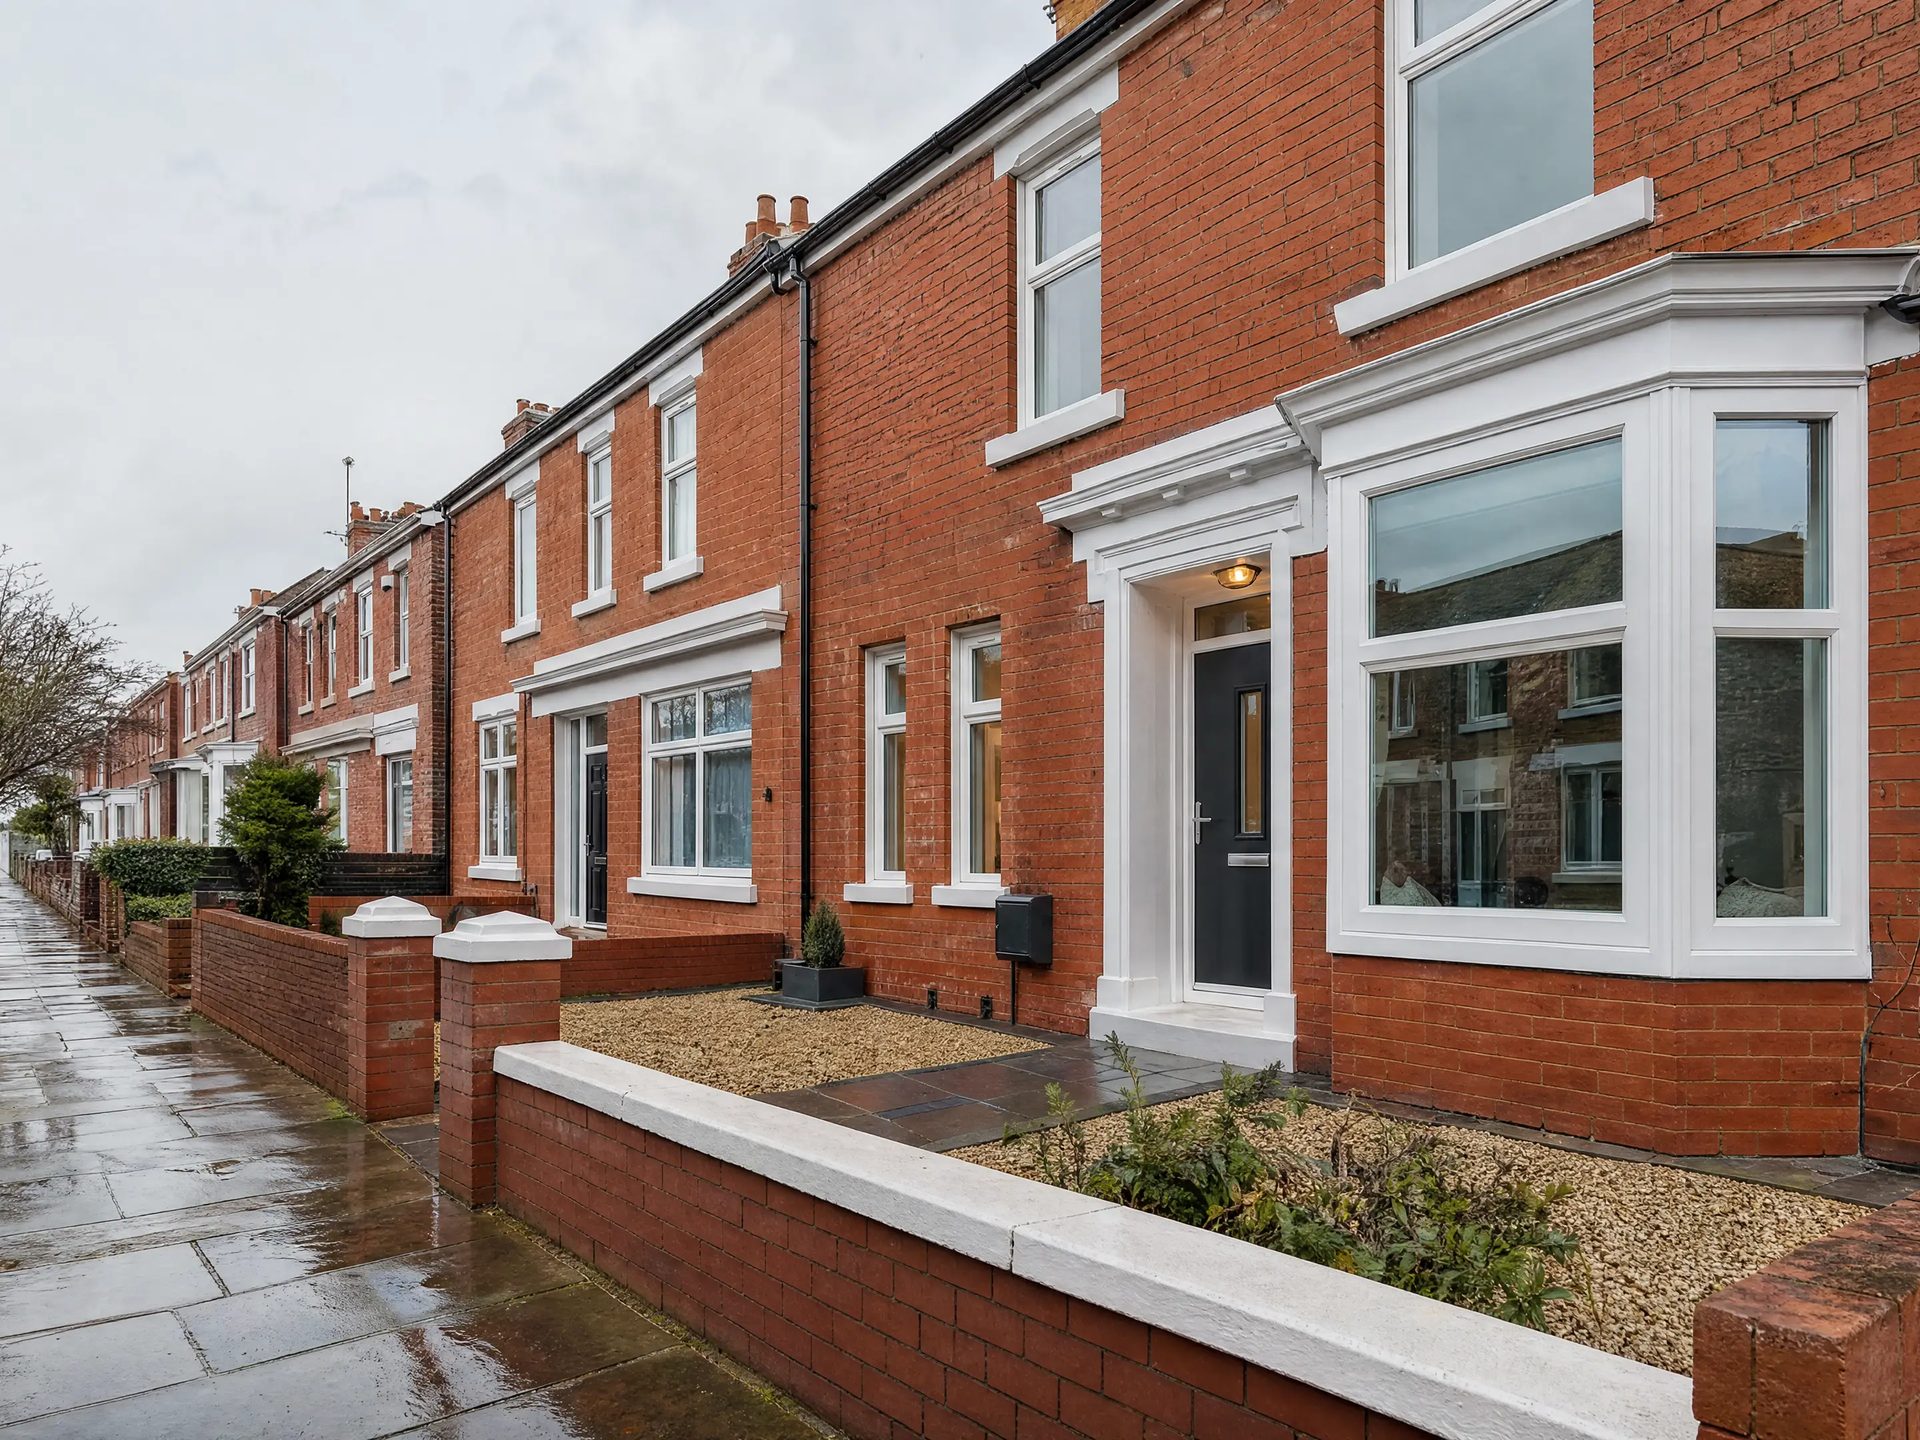
A fully renovated red-brick terraced house in the North East of England

The unit, as delivered — fully renovated and occupancy-ready at handover. Illustrative.

“Your income clock starts with your ownership, not with tenant placement.” UK social housing programme · lease terms
The same £127,500, as a calendar — illustrative.
WhenCash
Reservation£5,000 — secures the unit, deducted from price
On exchange of contracts50% of price · £63,750
On delivery — within 90 daysBalance of £58,750
One-time costs at purchaseLegal ~£1,550 + stamp 3–5% · £3,825–£6,375
Total capital in£132,875–£135,425
Day 91 — income startsFirst contracted payment
From Year 1£12,750–£15,300 net / yr · £1,062–£1,275 / mo
By Year 25£318,750–£382,500 cumulative net income — before CPI-linked uplifts

Worked example is illustrative of current UK programme terms. Net yield is property-specific within the 10–12% band and is confirmed in writing before reservation; one-time costs are estimates that vary by property. Past performance is not a guarantee of future returns. Property values and rental income can fall as well as rise. Global Investments Inc. Ltd provides international property advisory services and is not regulated by the UK FCA.

The tool

Run Your Own Numbers

Two dials and a stamp rate. The maths is the brochure’s maths — entry price, contracted net yield, legal and duty — with nothing hidden below the line.

Purchase price£127,500

Programme entry: from £127,500, fully renovated freehold.

Net yield10.0%

Property-specific band — the exact figure is contracted in writing before reservation.

Stamp duty

Programme estimate: 3–5% at purchase, property-specific.

Fixed in the maths — legal ~£1,550 at purchase · buildings insurance ~£400 / yr · management, maintenance, repairs £0 · cash purchase only.

All-in capital
£132,875
price + legal + stamp duty
Net income
£12,750/ yr
≈ £1,062 a month
Yield on all-in
9.6%
contracted net ÷ total capital in
Capital repaid by income in
10.4years
cumulative net income covers all-in capital — you still own the house
By Year 25
£318,750
cumulative net income, before CPI-linked uplifts
Contracted from
Day 91
the income clock starts with ownership
0510152025 yrs

Gold: cumulative contracted net income. Dashed: your all-in capital. The dot is the year income has repaid it — every year after, and the house itself, remain yours. CPI-linked uplifts (capped) are not modelled.

Illustrative tool, not investment advice. Net yield is contracted per property within the 10–12% band; legal, stamp duty and insurance are programme estimates that vary by property. Cash purchase only — the lease structure does not support mortgages. Past performance is not a guarantee of future returns. Property values and rental income can fall as well as rise. Global Investments Inc. Ltd provides international property advisory services and is not regulated by the UK FCA.

Questions

Asked Before You Ask

Is it genuinely hands-off?

Yes — the housing association is responsible for maintenance, repairs and tenant management under the lease. You receive contracted net income; there is no operating role.

Who pays the rent?

The housing association, under a legally binding lease funded by government-backed arrangements — not an individual tenant who might fall behind.

Is the income fixed?

The net yield sits in the 10–12% band and is fixed by the lease for your specific property — confirmed in writing before reservation, with income contracted from Day 91.

How do I exit?

Units are freehold and can be sold like any other property. The lease transfers with the title, which is what makes the asset attractive to the next income buyer.

Net yield is contracted under the lease with the housing association. Figures are illustrative of the current UK programme. Past performance is not a guarantee of future returns. Property values and rental income can fall as well as rise. Global Investments Inc. Ltd provides international property advisory services and is not regulated by the UK FCA.

Next step

See This Week’s UK Units

Tell us your budget and target income — we’ll send the current North East list before it goes public.

Talk to a UK specialist